- Despite strong retail investors’ appetite, ESG SIPs are not fully recognized by the EU Sustainable Finance Regulatory framework.
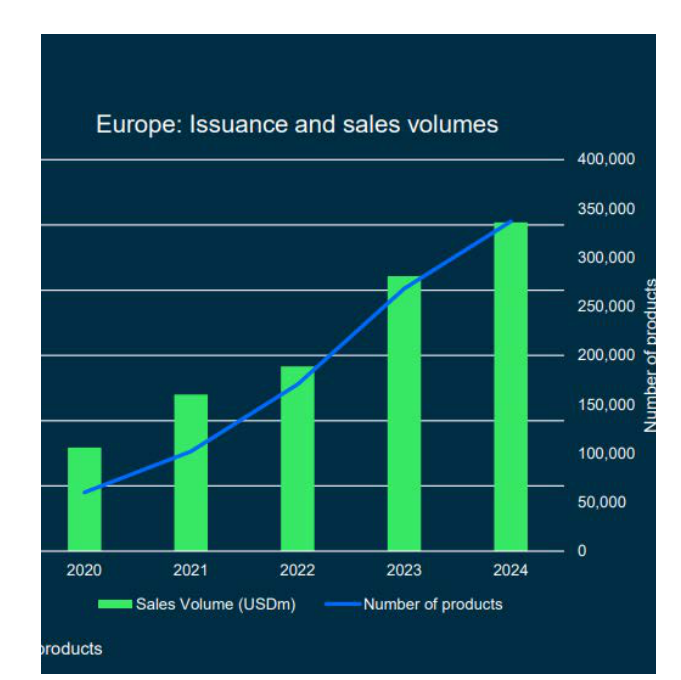
- However, with over EUR 300 bn of annual issuance, SIPs have become a fixture in advised retail investment solutions.
- SIPs allow investors’ risk profiles to be tailored to their risk appetite (e.g. through capital protection), enhancing their participation in the equity and credit markets while controlling their risk exposure.
- ESG SIPs are fully sustainable products. Through their bond and their option components, they contribute positively to the companies’ cost of capital , allowing to re-direct savings to more virtuous companies and sectors.
- ESG SIPs are not leveraged products nor derivatives, they are securities issued by banks as a bond (including environmental or social bond) that offer capital protection and exposure to ESG assets.
- ESG SIPs’ sustainability features are measurable. The ESG assessment is made at the issuer and underlying asset level (bond and performance components).
- The current SFDR regime creates an unfair level playing field between ESG investment products, to the detriment of SIPS in contrast to the other products that are currently recognized under SFDR.
- Including SIPs in SFDR would harmonize the currently fragmented and gold-plated EU 27 regimes and bring coherence to the EU Sustainable Regulations*, as recommended by the Draghi report.
- It would also foster capital allocation towards a more sustainable economy.
(*e.g. current gap with MIFID ESG Preferences with which SIPs manufacturers and distributors must comply with when defining ESG target market and ESG products criteria).
Updated version : 12 December 2025
SFDR
&
Structured Investment Products
The case for the inclusion of structured investment products (SIPs) in SFDR
1.1 Structured Investment Products (SIPs)
SIPs are hybrid investment vehicles (bond + option)
Technically, SIPs are hybrids. They combine:
- a bond component (“the safety engine”) : where part of the capital is invested in a bond (zero-coupon) maturing at the product’s end date, preserving the initial capital, and
- an option component (“the performance engine”) which is exposed to the underlying assets (usually equity, either single share, basket of shares or index).
Economically : equivalent to bonds with conditional coupons linked to the performance of the underlying assets. Legally: debt securities (e.g. Euro Medium-Term Notes or EMTNs) issued by credit institutions.
1.2 Structured Investment Products
SIPs have become a reference in advised investment solutions for retail
- With over EUR 300 bn of annual issuance structured investment products (SIPs) such as structured notes (e.g. EMTNs) have become a fixture in advised retail investment solutions, with a portfolio diversification approach, notably with a capital protection perspective.
- These investment products are distinct from flow leverage products (e.g. turbos );
- They are principally equity and equity-index based products.
Source SRP report Europe Market Overview 2024 (18 March 2024)
2. SIPs contribute to the ESG ecosystem
Double contribution through bond component and exposure to equity markets
- Similarly to ESG funds, ESG SIPs contribute positively to the companies’ cost of capital (cost at which they can finance themselves in the future) via the economic exposure to these companies’ shares and debt that these products provide.
- ESG SIPs allow to send a signal to the market by re-directing savings to more virtuous companies and sectors.
- For retail investors with ESG preferences, ESG SIPs are the only ESG financial instruments offering capital protection tailored to their risk appetite, while allowing participation in the equity markets
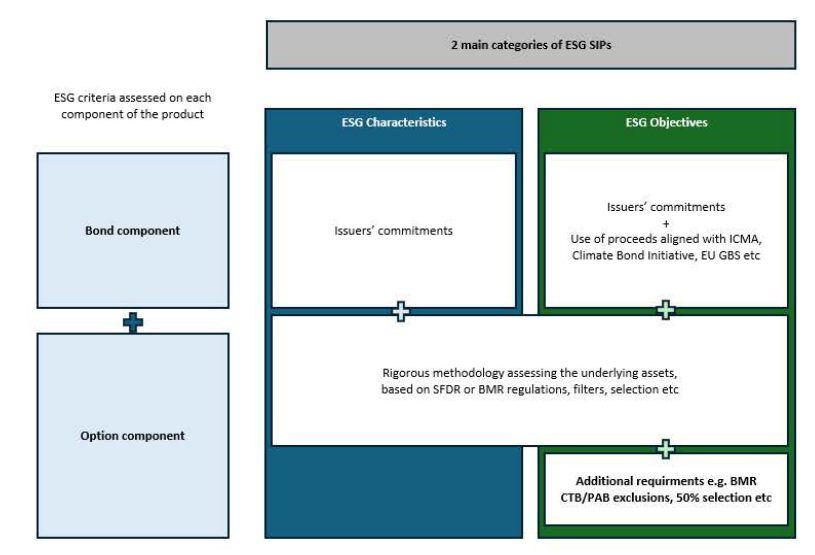
- ESG SIPs offer a spectrum of ESG contribution of their respective components (bond and performance).
- This gamut of ESG possibilities ranges from structured green bonds with full use of proceeds and full ESG exposure to general-purpose structured bonds with ESG underlying.
Annexes
- ESG SIPs: example of a product based on an ESG index
- ESG SIPs: a fair value for money
- ESG Regulations: a patchy framework
- ESG SIPs: measurement, Yes we can!
- ESG Transition: crucial role of secondary markets
1. SIP – example
Structured Investment Product based on an ESG filtered Eurostoxx 50 index
The underlying asset (performance component) is the EURO STOXX 50 ESG X Index based on the parent EURO STOXX 50 with specific ESG features.
ESG-X Index methodology:
The index is based on the parent pan-European equity index Euro Stoxx 50 with specific ESG exclusions:
Companies in controversial weapons, coal, tobacco.
- Companies violating UN Global Compact principles.
- Companies with low ESG scores as calculated, for
- example, by Sustainalytics. The total of the excluded companies represent 20%
- of the companies comprised in the EURO STOXX50.
Additions: each excluded company is replaced by a
- company belonging to the EURO STOXX 50 belonging to the same sector but with a better ESG score.
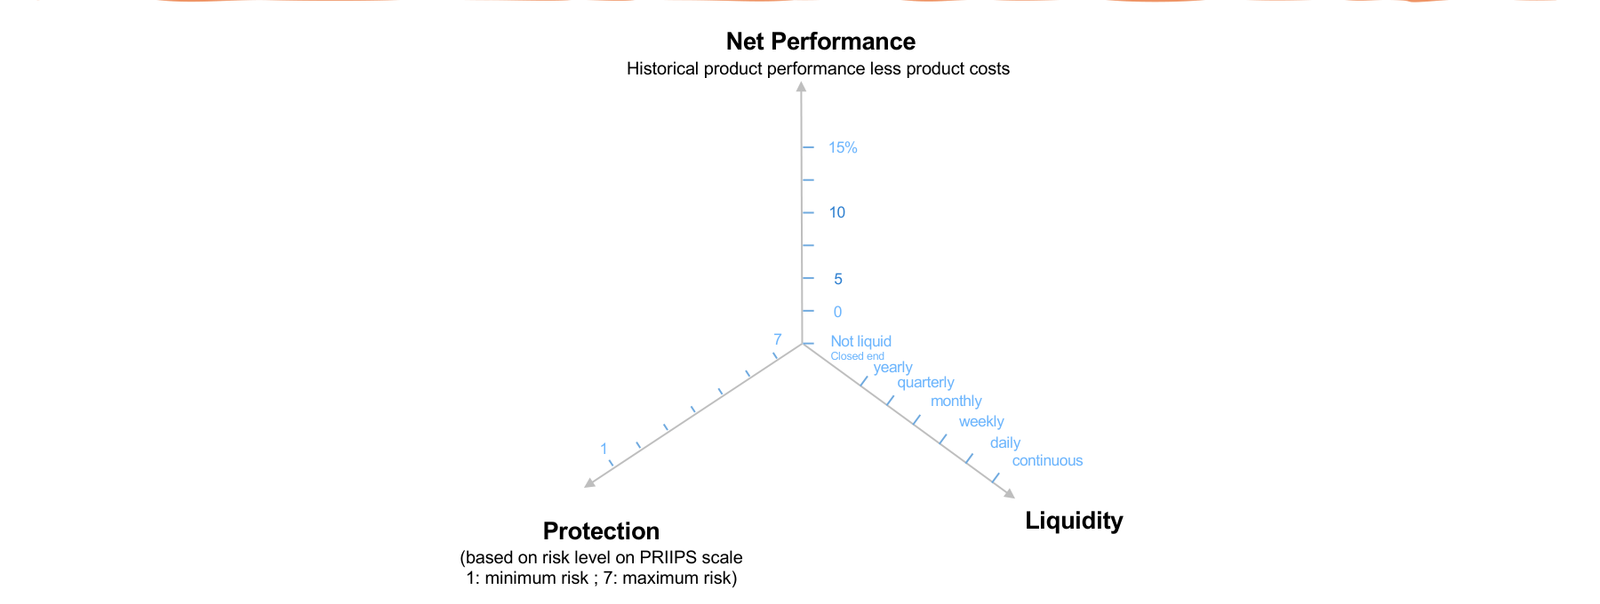
2.1 Investment in a nutshell:
a balancing act
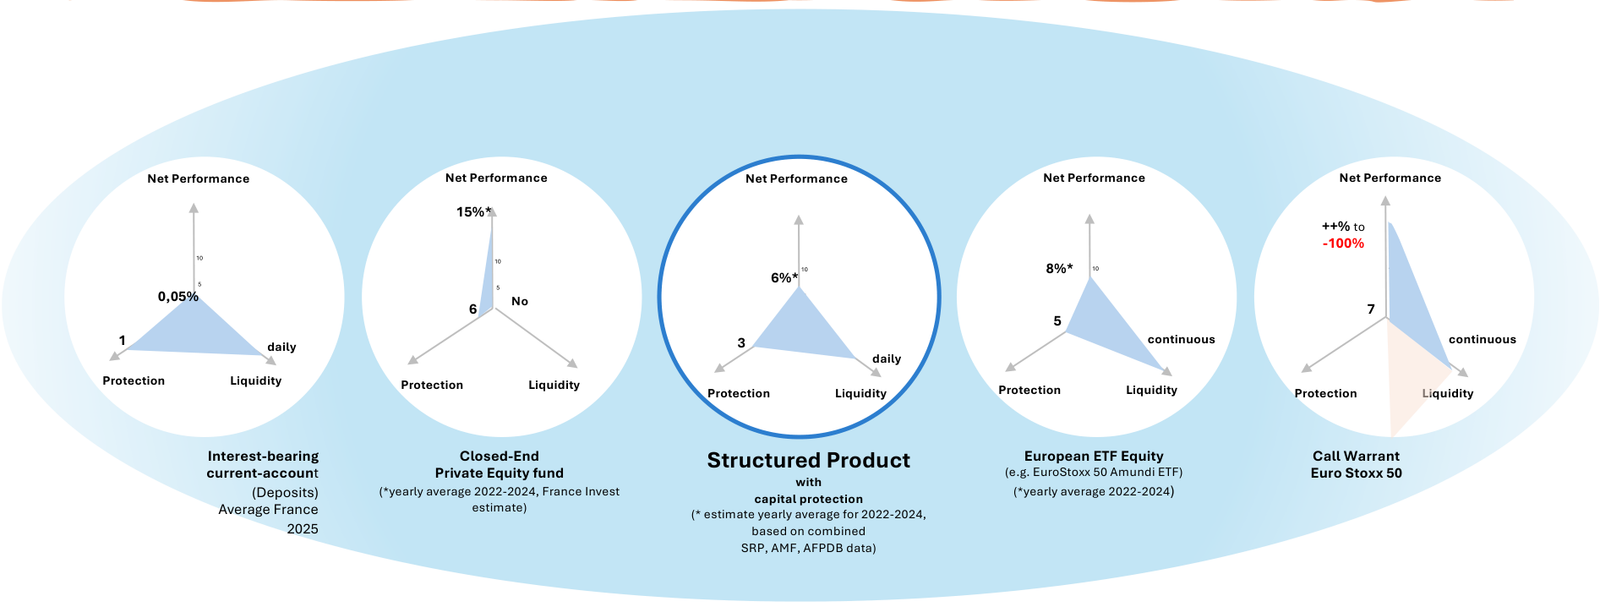
2.2 SIPs a fair value for money…
2.3 SIPs:
stability and protection
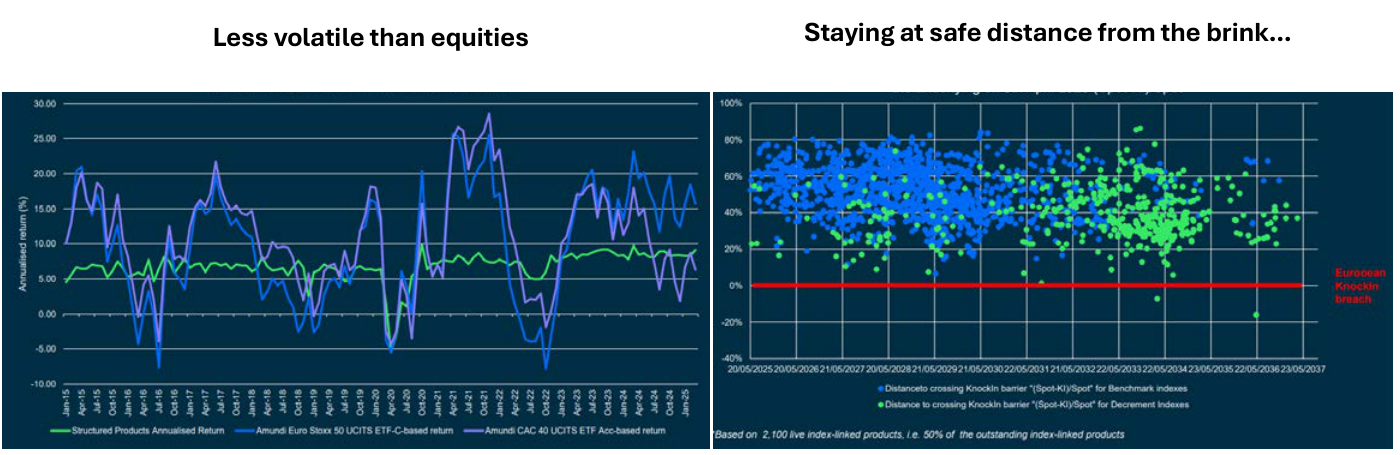
Structured products offer a more stable return than equity ETFs which are more volatile (Source: SRP)
The distance to the knock-in barrier represents the “safety buffer” of structured products. Even in adverse market conditions (e.g. April 9, 2025), this distance remains important (52,6% for benchmark indices in blue on the graph , 38,1% for decrement indices, in green on the graph) (Source: SRP)
2.4 SIPs:
a stable and positive return distribution
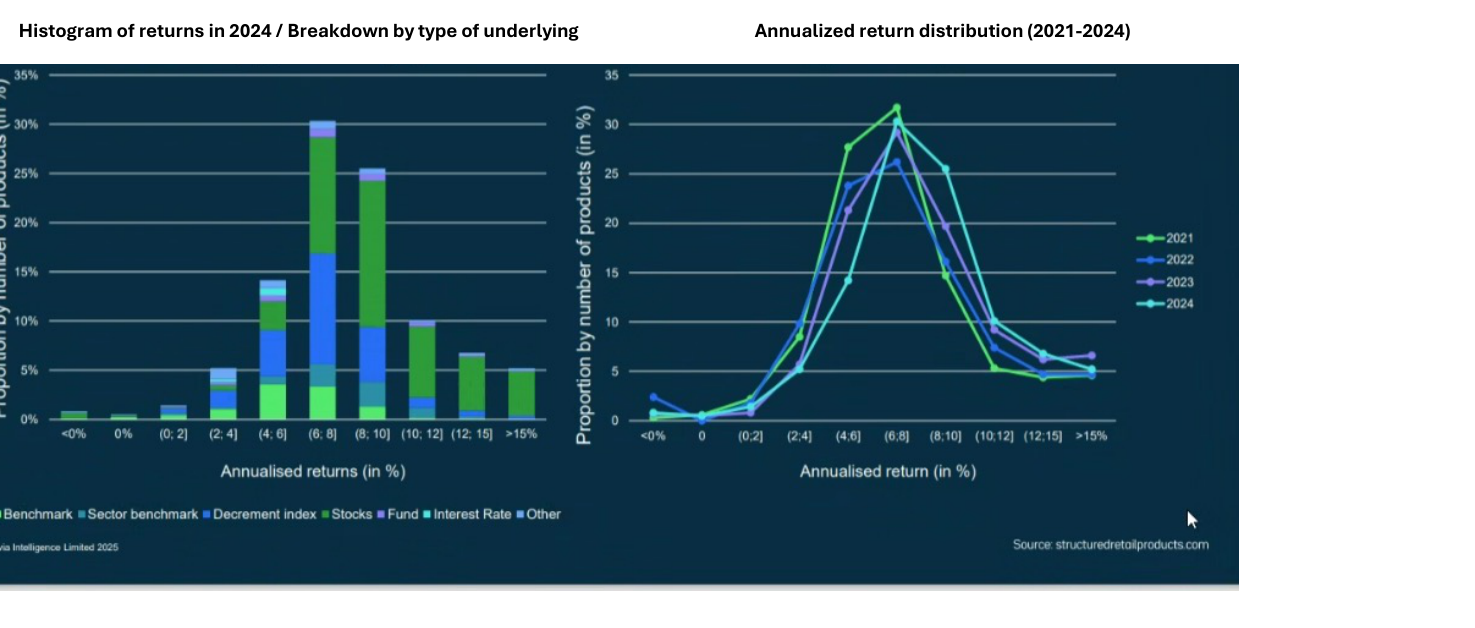
Performance net of product costs (not including wrapper costs). Wrapper costs are inexistent or insignificant for instruments held in plain securities accounts and in the order of 1% for life-insurance contracts for France.
3.1 Sustainable finance regulatory framework
Flaws affecting SIPs
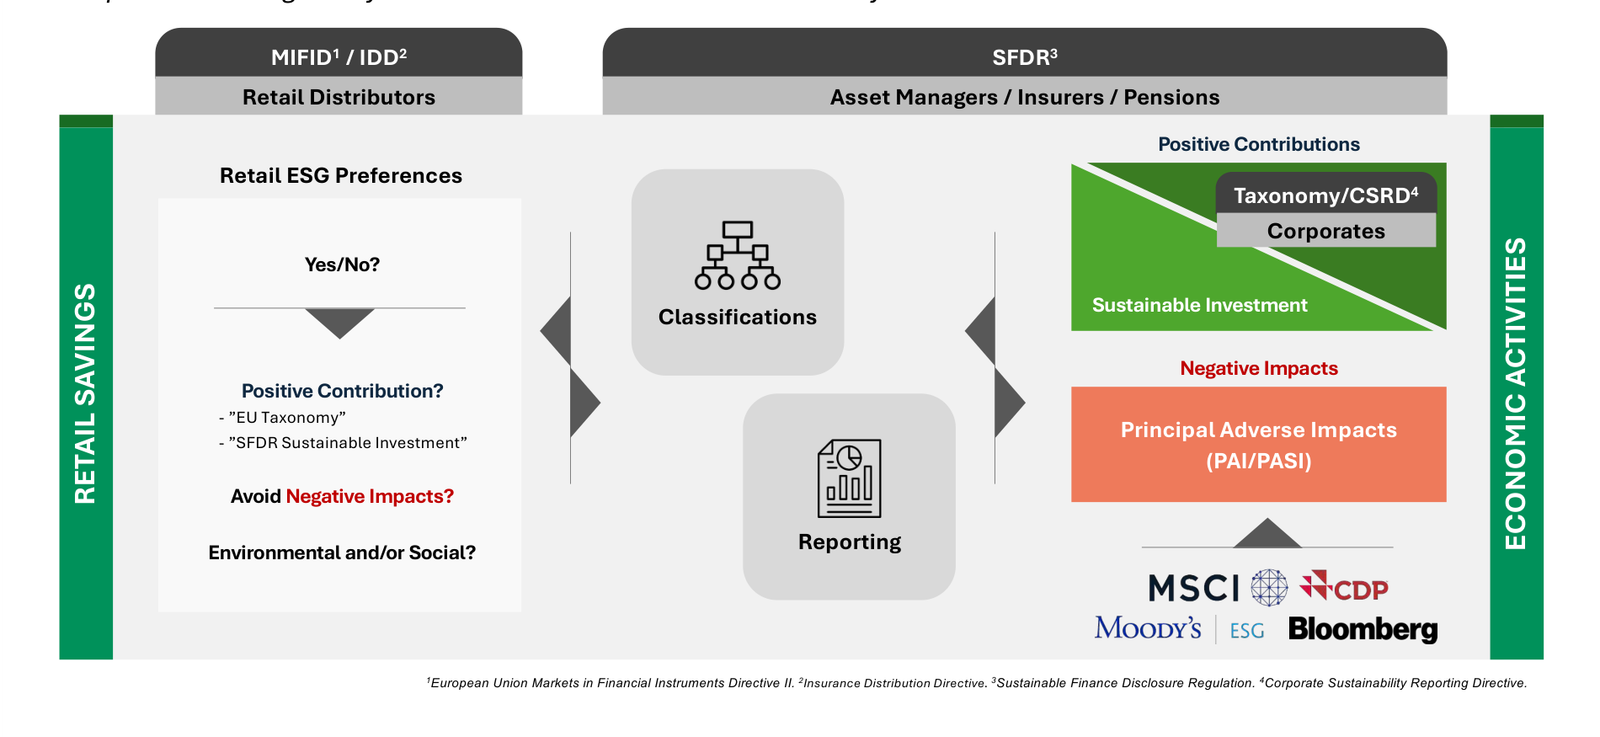
The EU SFDR regulation governs sustainable funds products and applies to asset managers and other related fund-like products.
- In MiFID/IDD, the ESG criteria that define a “Sustainable MiFID product” use the SFDR concepts. MiFID product scope is wider than SFDR product scope as its covers all financial instruments (e.g. shares, bonds…) including SIPs.
- Whilst SIPs’ offering to retail investors with sustainability preferences is excluded from SFDR, they must comply with MiFID Sustainability Preferences criteria which are defined under SFDR.
- This regulatory gap creates legal uncertainty for manufacturers and investors and an unlevel playing field with other recognised EU sustainable investment products.
- Including SIPs in SFDR would provide standardized, harmonized and proportionate disclosures to investors, improving their protection, and transparency on the sustainable finance ecosystem and solutions, in line with the ESMA/ESAs and SMSG opinions and Prospectus Regulation (PR3). Finally, PRIIPs will rely on SFDR for ESG products’disclosure.
- As per Draghi’s report, their inclusion would contribute to simplification and efficiency: SIPs are currently implemented differently across 27 EU countries.
- Inclusion would require disclosure and assessment adjustments to reflect that SIPs, unlike active managed funds, are not managed products. Assessment of SIPs sustainable features are to be made at issuance of the product and not on an ongoing basis that is only feasible for active managed products.
3.2 Sustainable Finance Regulatory Framework
A European Union Regulatory Framework in need of further consistency…
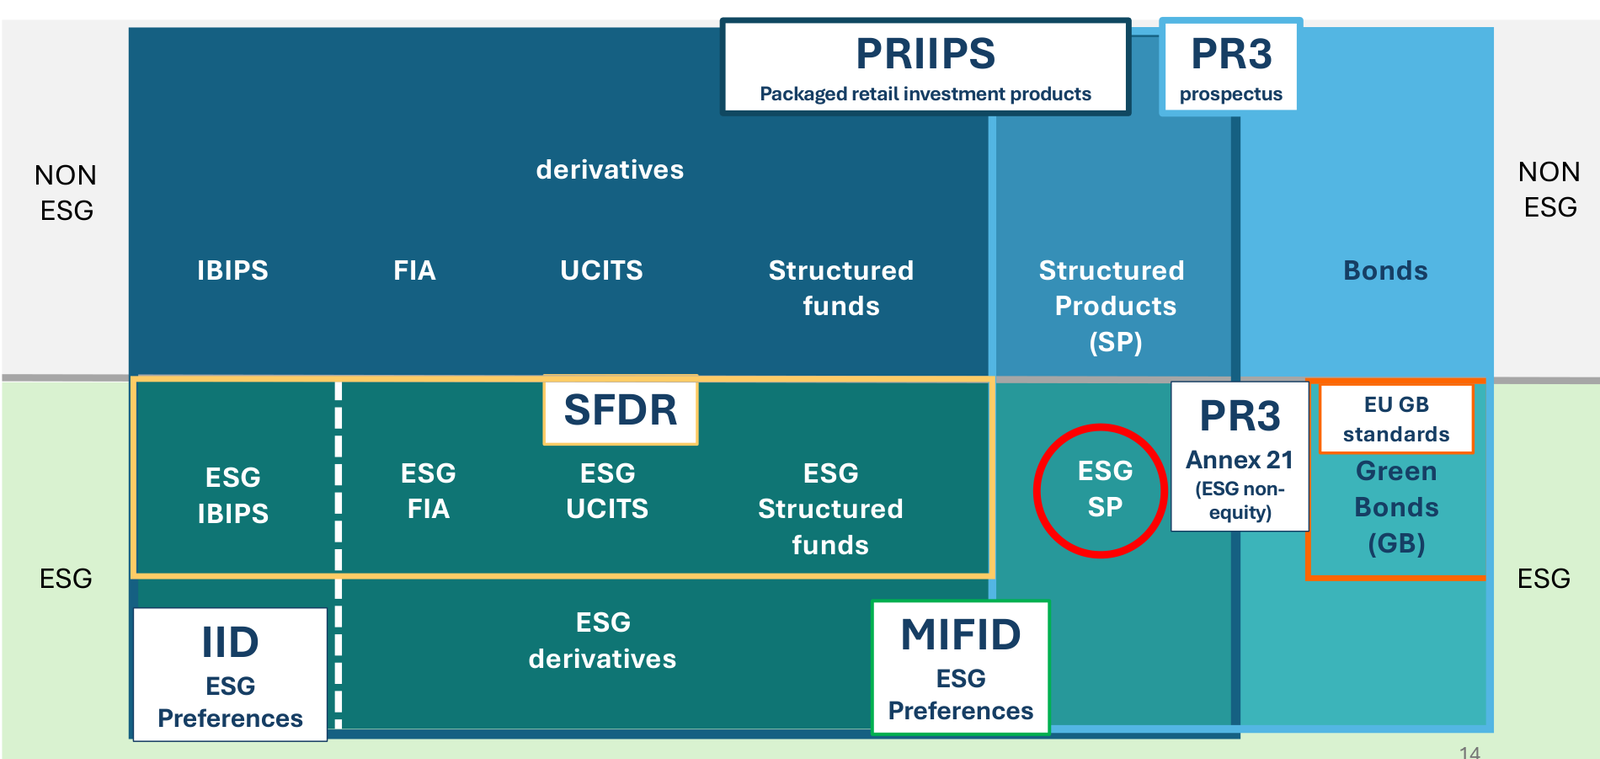
3.3 Sustainable Finance Regulations: disclosure and suitability: PRIIPS PR3
a patchy framework
4. Measuring SIP ESG contribution:
Yes, we can…
- As hybrid investment vehicles, structured investment products may provide a full range of combination of the respective ESG contribution of their two components (funding and performance components).
- This ranges from the structured green bonds with a full use of proceeds and a full ESG exposure, to the general purpose structured bonds with an ESG underlying.
- The ESG contribution (i.e. percentage of sustainable investment and/or PAI, as set-out in Art 2.17 of SFDR) of each component may be assessed for each component.
- As for the optional part, the level of exposure to the ESG underlying (e.g. shares of an ESG best-in-class index) may be assessed by the delta of the product (i.e. exposure to the equity underlying) at issuance, with a hair-cut accounting for possible delta variation during the product life until its maturity.
5.1 Rising up to the decarbonization challenge
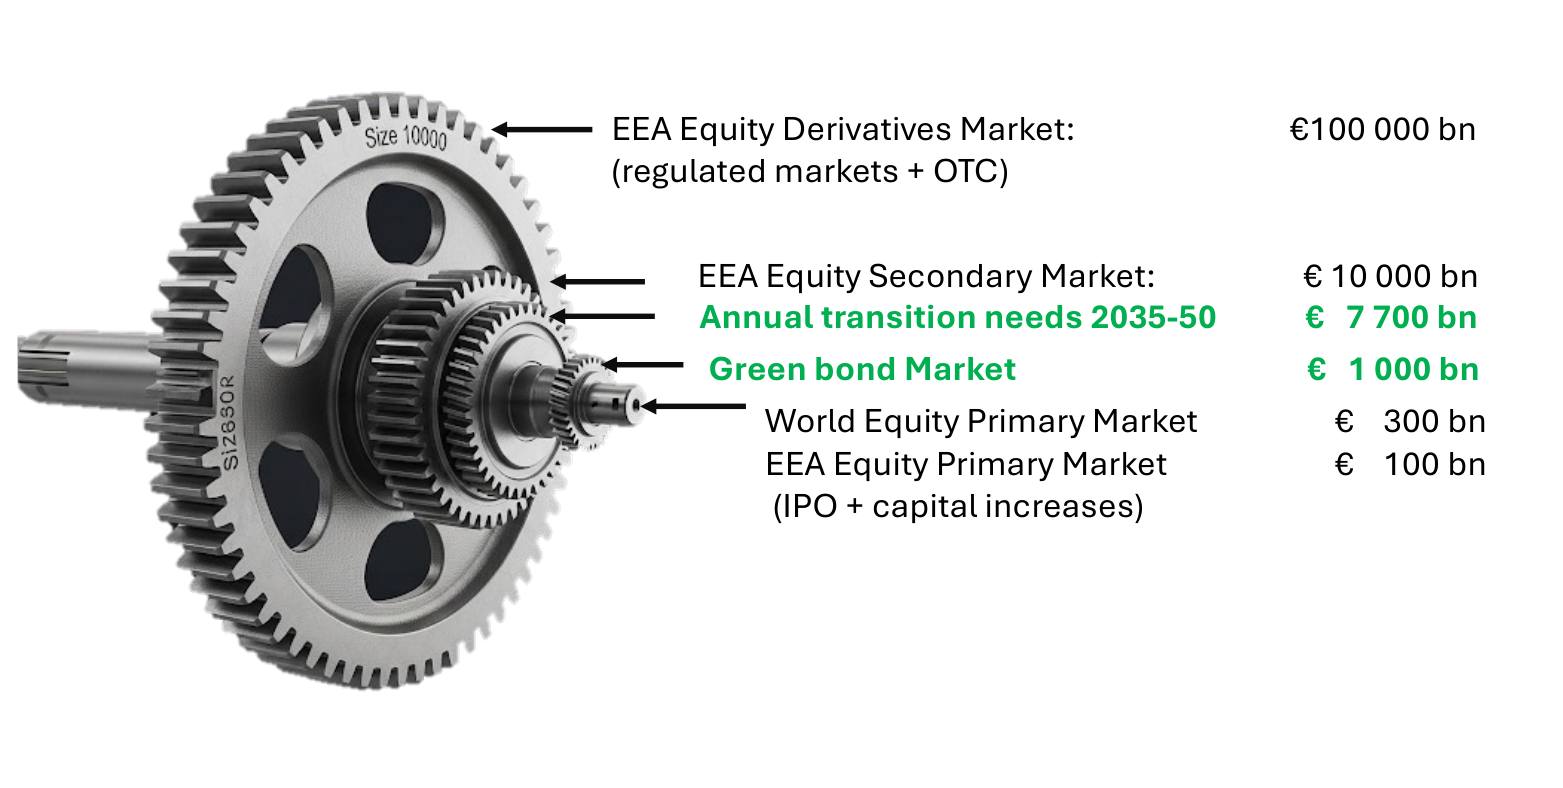
Transition costs far exceeding the sole primary capital markets’ capacity
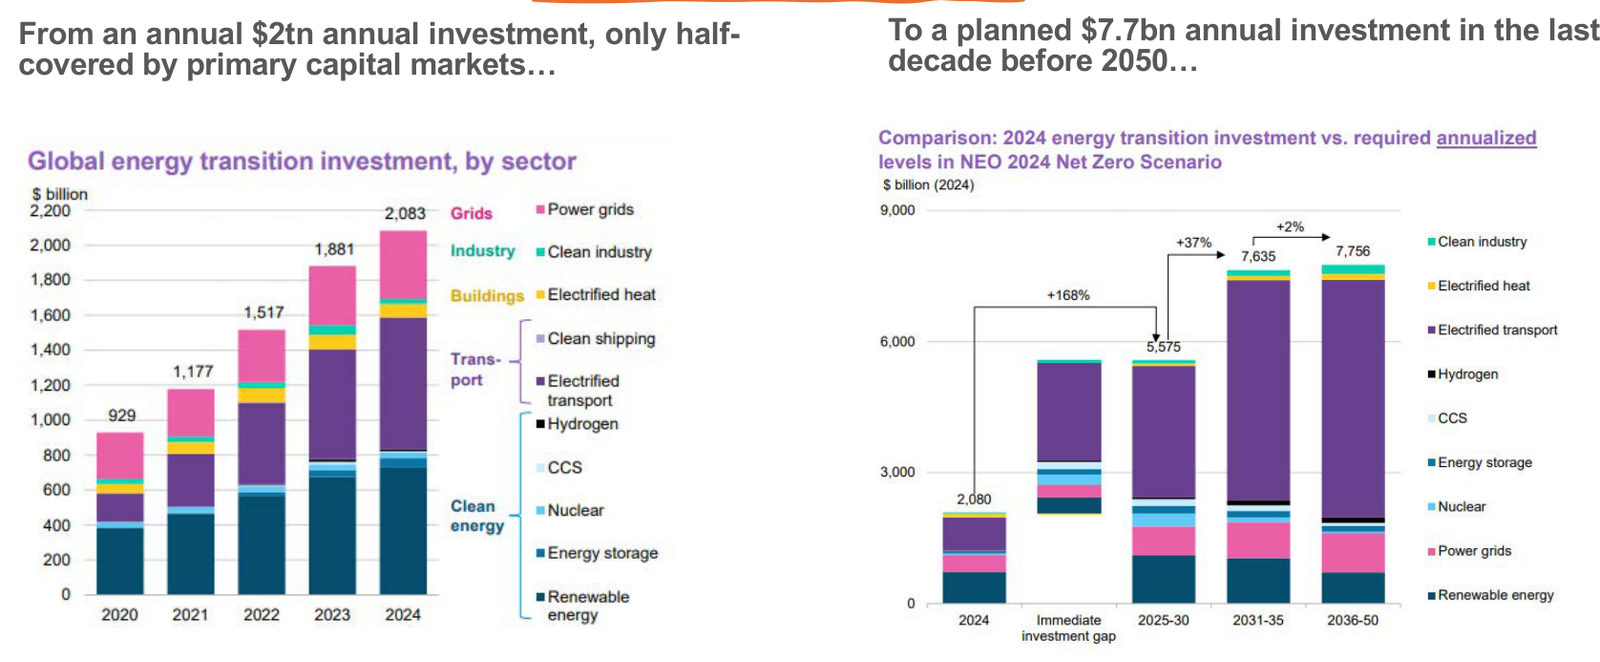
Source : BloombergNEF Energy Transition Investment Trends 2025
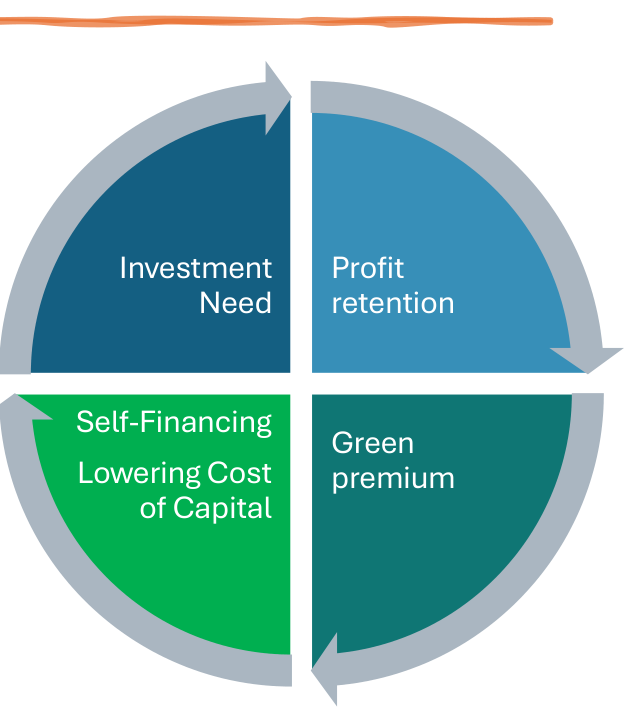
5.2 The virtuous transition self-financing circle
the crucial role of ESG strategies on secondary markets
- At present, primary capital markets cover only a half of the annual energy transition needs of $2tn (with equity and debt primary markets accounting respectively for $50bn and $1tn).
- Therefore, corporate issuers must self-finance around half of their transition investments. (with even more self-financing needs in the decades to come).
- This self-financing is directly linked to issuers’ ability to retain part of their profits.
- As profit retention is opposed to dividend payment, it is dependent on issuers’ ability to compensate for this present loss of opportunity with the promise of a future value gain.
- ESG best-in-class and exclusion filtering strategies, as devised in equity indices, reward issuers that follow a credible transition strategy. The selected issuers composing these indices will benefit from an increased secondary-market liquidity (which, in turn, lowers their cost of capital / refinancing cost) also known as the Green Premium.
- This additional liquidity supports a potential of valuation gain of issuers’ securities, guaranteeing their long-term self-financing capacity.
- ESG structured investment products and their underlying ESG indices allow to send a signal to the market by redirecting savings and capital flows to more virtuous companies and sectors.
5.3 Moving-up a gear from primary to secondary
Transition costs far exceeding the sole primary capital markets’ capacity
Glossary
Autocall (auto-callable product)
An autocall is a structured product which matures early if the underlying has reached a pre-determined level on a specific date during the product term.
For example, a growth product might offer a minimum return of 100% plus 100% of the rise in the EuroStoXX50 index after six years but pay out 130% after three years if the index has risen by 30% or more at this date
Decrements
Decrement indices are synthetic indices based on a reference index (either broad market or single stock), from which a fixed amount is periodically deducted to represent expected dividends. This decrement is applied either as a percentage (typically 5% per year) or as a fixed number of index points. The primary objective of decrement indices is to offer predictability in performance by “fixing” the dividend in advance, allowing for higher coupon payments while mitigating dividend risk for issuers. These indices have grown in prominence in structured product design since the mid-2010s. [Source: RegExchange]
EMTN
Euro Medium Term Notes (or EMTNs) are a type of debt issuance program that allows issuers (banks, corporate or sovereign) to issue continuously, under the same base prospectus – complemented by Final Terms for each specific product issuance.
Wrapper
Wrapper: legal or financial structure that encloses a financial asset or a group of those assets, typically to provide specific features, such as tax advantages. As an example, on the French structured product market, life-insurance contracts are the most common wrapper (80% of the distribution). Here the life-insurance contract holds the underlying instruments (units) whether structured products or UCITS.
Knock-In barrier
A knock-in barrier is a key conditional feature that determines whether a specific risk (or payoff) becomes active. For product with condition capital protection, this barrier is typically set below the initial level of the underlying (e.g. 60% of the initial reference equity-index level). If the barrier is breach, the protection may disappear (e.g. receive 58 of invested amount if index drops to 58% of its initial level). It the barrier is never breached (i.e. knock-in not activated) the investor benefits from capital protection and of favourable payoff terms. [The SRP graph on slide 6 shows the safe distance between equity index structured products levels and their respective knock-in barriers].
Zero Coupon bond : a bond bought at a price lower than its face value, with the face value repaid at the time of maturity). For structured products, it is the “safety engine” of the product (a.k.a. funding component)
Authoritative PDF version: SFDR & Structured Investment Products – AFPDB, 22 July 2025 (PDF).